

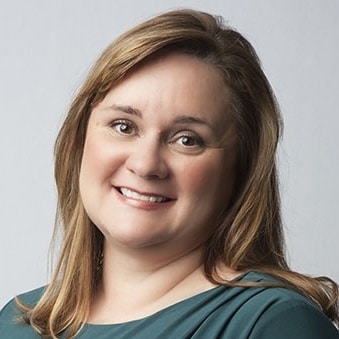
Pamela Perdue
Title: Executive vice president and chief regulatory officer, Continuity
Age: 51
Industry experience: 29 years
In a time when regulation is always changing and has never been more complex, financial institutions need to do everything they can to keep up. Pamela Perdue knows this first-hand. She began her career in banking in 1990 as a stockbroker until a compliance breach shut the firm down overnight – higher-ups at the company had committed many violations, including what amounted to running a Ponzi scheme.
After that experience, Perdue made the leap into traditional banking compliance, where she worked at a number of large and small banks and then as an examiner with the Federal Reserve system. But always an entrepreneur at heart, Perdue used her expertise to launch several startups including Compliance Compass and MyComplianceInfo. Her fourth regtech venture, New Haven-based Continuity, is a fully automated compliance management system for banks and credit unions that combines people and technology to reduce the burden of compliance.
Q: Why was Continuity founded?
A: Continuity wasn’t the only big news in regulation when we launched in 2008 – you may recall this thing called the Dodd-Frank Act taking center stage that year. We launched into the mouth of the recession at a time when banks and credit unions were rapidly being shuttered, due in some part to the massive regulatory burden that Dodd-Frank created. The avalanche of regulation made operating conditions unbearable for community banks and credit unions, and our group of cofounders knew there was a better way to manage that burden through technology.
Q: What problem does it solve?
A: Regulatory risk can best be summed up for the layperson along three lines: the risk of missing something, misinterpreting something or mishandling something. Continuity’s compliance management system reduces the chances of these misfires. It’s a unified software platform where the specific, day-to-day operational tasks of compliance get done. With everything in one place, visibility into where things stand is enhanced. With consistent tracking and reporting, accountability improves. All of this translates into less time and less money directed toward compliance – all without compromising results.
Q: Since the implementation of Dodd-Frank, what do you think has been the biggest challenge for financial institutions when it comes to complying with regulation?
A: The biggest challenge has been the pace of regulatory change. We have higher volume and higher velocity than ever before. In 2018 alone, there were more regulatory changes (256) than there were business days in the year (249). Now, add on top of that, these changes are more complicated. And all of those words represent the reality that they touch more products and services, as well as more roles inside the financial institution, than rules did prior to 2008. This complexity leads to confusion among the industry as new rules are rolled out, and that confusion in turn must be addressed by – you guessed it – more regulatory updates. The incessant repetitive cycle of change, update and revise is every compliance professional’s worst enemy.
Q: How do RegAdvisor Pro and RegControls streamline compliance?
A: RegAdvisor Pro pulls in data from government sources, analyzing information through a combination of machine and human effort. Implementation plans are distributed only to those institutions affected by the change, and only those employees who need to take action are notified. Compliance effort drops 90 percent compared to manual methods. RegControls includes pre-built compliance procedures that are automatically updated when regulations change. Technology alleviates the arduous task of perpetual updates, while ensuring that staff don’t rely on obsolete information. An add-on controls builder feature lets clients build their own custom controls using a simple interface that requires no advanced technical expertise. Both of these products can be up and running in 30 days or less.
Q: With national political turmoil and regulatory changes, how can financial institutions best prepare themselves for incoming regulation?
A: First, make sure you’re basing decisions on data, not hype or emotion. Many bankers were surprised to learn that despite regulatory “relief” being promised by Senate Bill 2155, actual relief did not materialize and 2018 had the greatest number of regulatory changes on record. Every change, no matter how small nor how favorable, triggers strategic and operational changes inside financial institutions, so gathering the right data and interpreting it correctly is key to success.
Second, understand that the changing environment demands new skill sets from risk and compliance officers, and hire accordingly. These teammates are increasingly called upon to demonstrate proficiency in data literacy, business intelligence and technology implementation and integration. Even professionals with MBAs and JDs can find themselves falling behind their more tech-savvy peers if they don’t adapt to modern methods.
Third, base your decisions on when to modernize or upgrade technology upon the overall return on investment, not just the up-front cost. If an affordable technology can prevent you from hiring even one new employee to deal with one changed regulation, it has paid for itself from inception. And when that same technology can continue to streamline your approaches year after year, those savings quickly add up to a meaningful financial result.
Perdue’s Five Compliance Trends to Watch in 2019
- Greater volatility in the broader economic markets.
- Confusion about how to implement regulatory “relief,” while regulators issue limited guidance.
- More enforcement actions against individual officers and directors, even when their institutions are not cited.
- Banks and credit unions will increasingly turn to regulatory technology to handle compliance burdens and challenges.
- Compliance and risk professionals will be expected to have strong skill sets in data analysis, business intelligence and technology integrations.