


Despite stagnant asset growth, Simsbury Bank & Trust and its parent company SBT Bancorp had performed well in recent years.
The company reported solid profits and grew its return on assets to 0.97 percent at the end of 2018.
But when a proposal came in from Liberty Bank last year to buy the bank, Simsbury President and CEO Martin Geitz said the company’s board of directors still felt it was in the best interest of shareholders.
Liberty Bank announced in March that it would merge with and absorb Simsbury Bank & Trust and SBT Bancorp for $51.32 per share in cash, giving the transaction a value of approximately $71 million.
The board felt the price was fair, Geitz said, and felt it would benefit Simsbury’s customers – who would get an expanded product set and higher lending limits – and the bank’s employees, most of whom will get to keep their jobs.
In addition, though, Simsbury’s board knew the roughly $480 million-asset bank would have a difficult time continuing to meet growth expectations from its shareholders as a publicly-traded bank.
“One of the challenges is that we have grown our ROA into the 90s, yet the market really wants to see 120 [basis points],” Geitz told The Commercial Record. “For a bank with our size and scale, to make that next jump was daunting. Dodd-Frank is a real thing that costs us money and holds us back from having that type of earnings performance.”
Regulation hasn’t been the only thing that has made future growth difficult for Simsbury.
Keeping up with technology is another challenge that Geitz sees down the road. The bank has deliberately invested in technology such as online banking to keep up with customers’ demand, but customers always want more, and partnering with fintech companies and purchasing more technology solutions is expensive, yet each year there are new ideas and products that banks really need in order to stay competitive, he said.
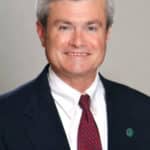
Simsbury Bank President and CEO Martin Geitz.
The third main challenge is the state’s economy. While there have been some bright lights, population growth has been minimal, leaving very few growth opportunities for banks.
“As a bank, the way we grow is by stealing somebody else’s business,” Geitz said. “It’s not like Boston or Texas where you can grow because new people are moving in and creating new customers and new businesses.”
The problem is not unique to Simsbury Bank, as other publicly traded banks in Connecticut have been gobbled up recently.
People’s United Bank closed on its acquisition of Farmington Bank and its parent company in an all-stock transaction valued at roughly $544 million in November 2018. A month later the parent company of Holyoke, Massachusetts-based PeoplesBank completed its acquisition of The First National Bank of Suffield.
Also in December, Berkshire Bank announced its plan to acquire the parent company of Willimantic-based Savings Institute Bank & Trust in an all-stock transaction valued at $180 million.
That leaves 11 smaller publicly traded banks left in Connecticut, according to Geitz, who said he could certainly see many of them being successful, but only if they focus on standing apart from the crowd.
“As smaller banks, they need to differentiate and find some way to fill a niche or strategy not being addressed by other bigger banks,” he said. “I wouldn’t write them off yet.”