

iStock photo
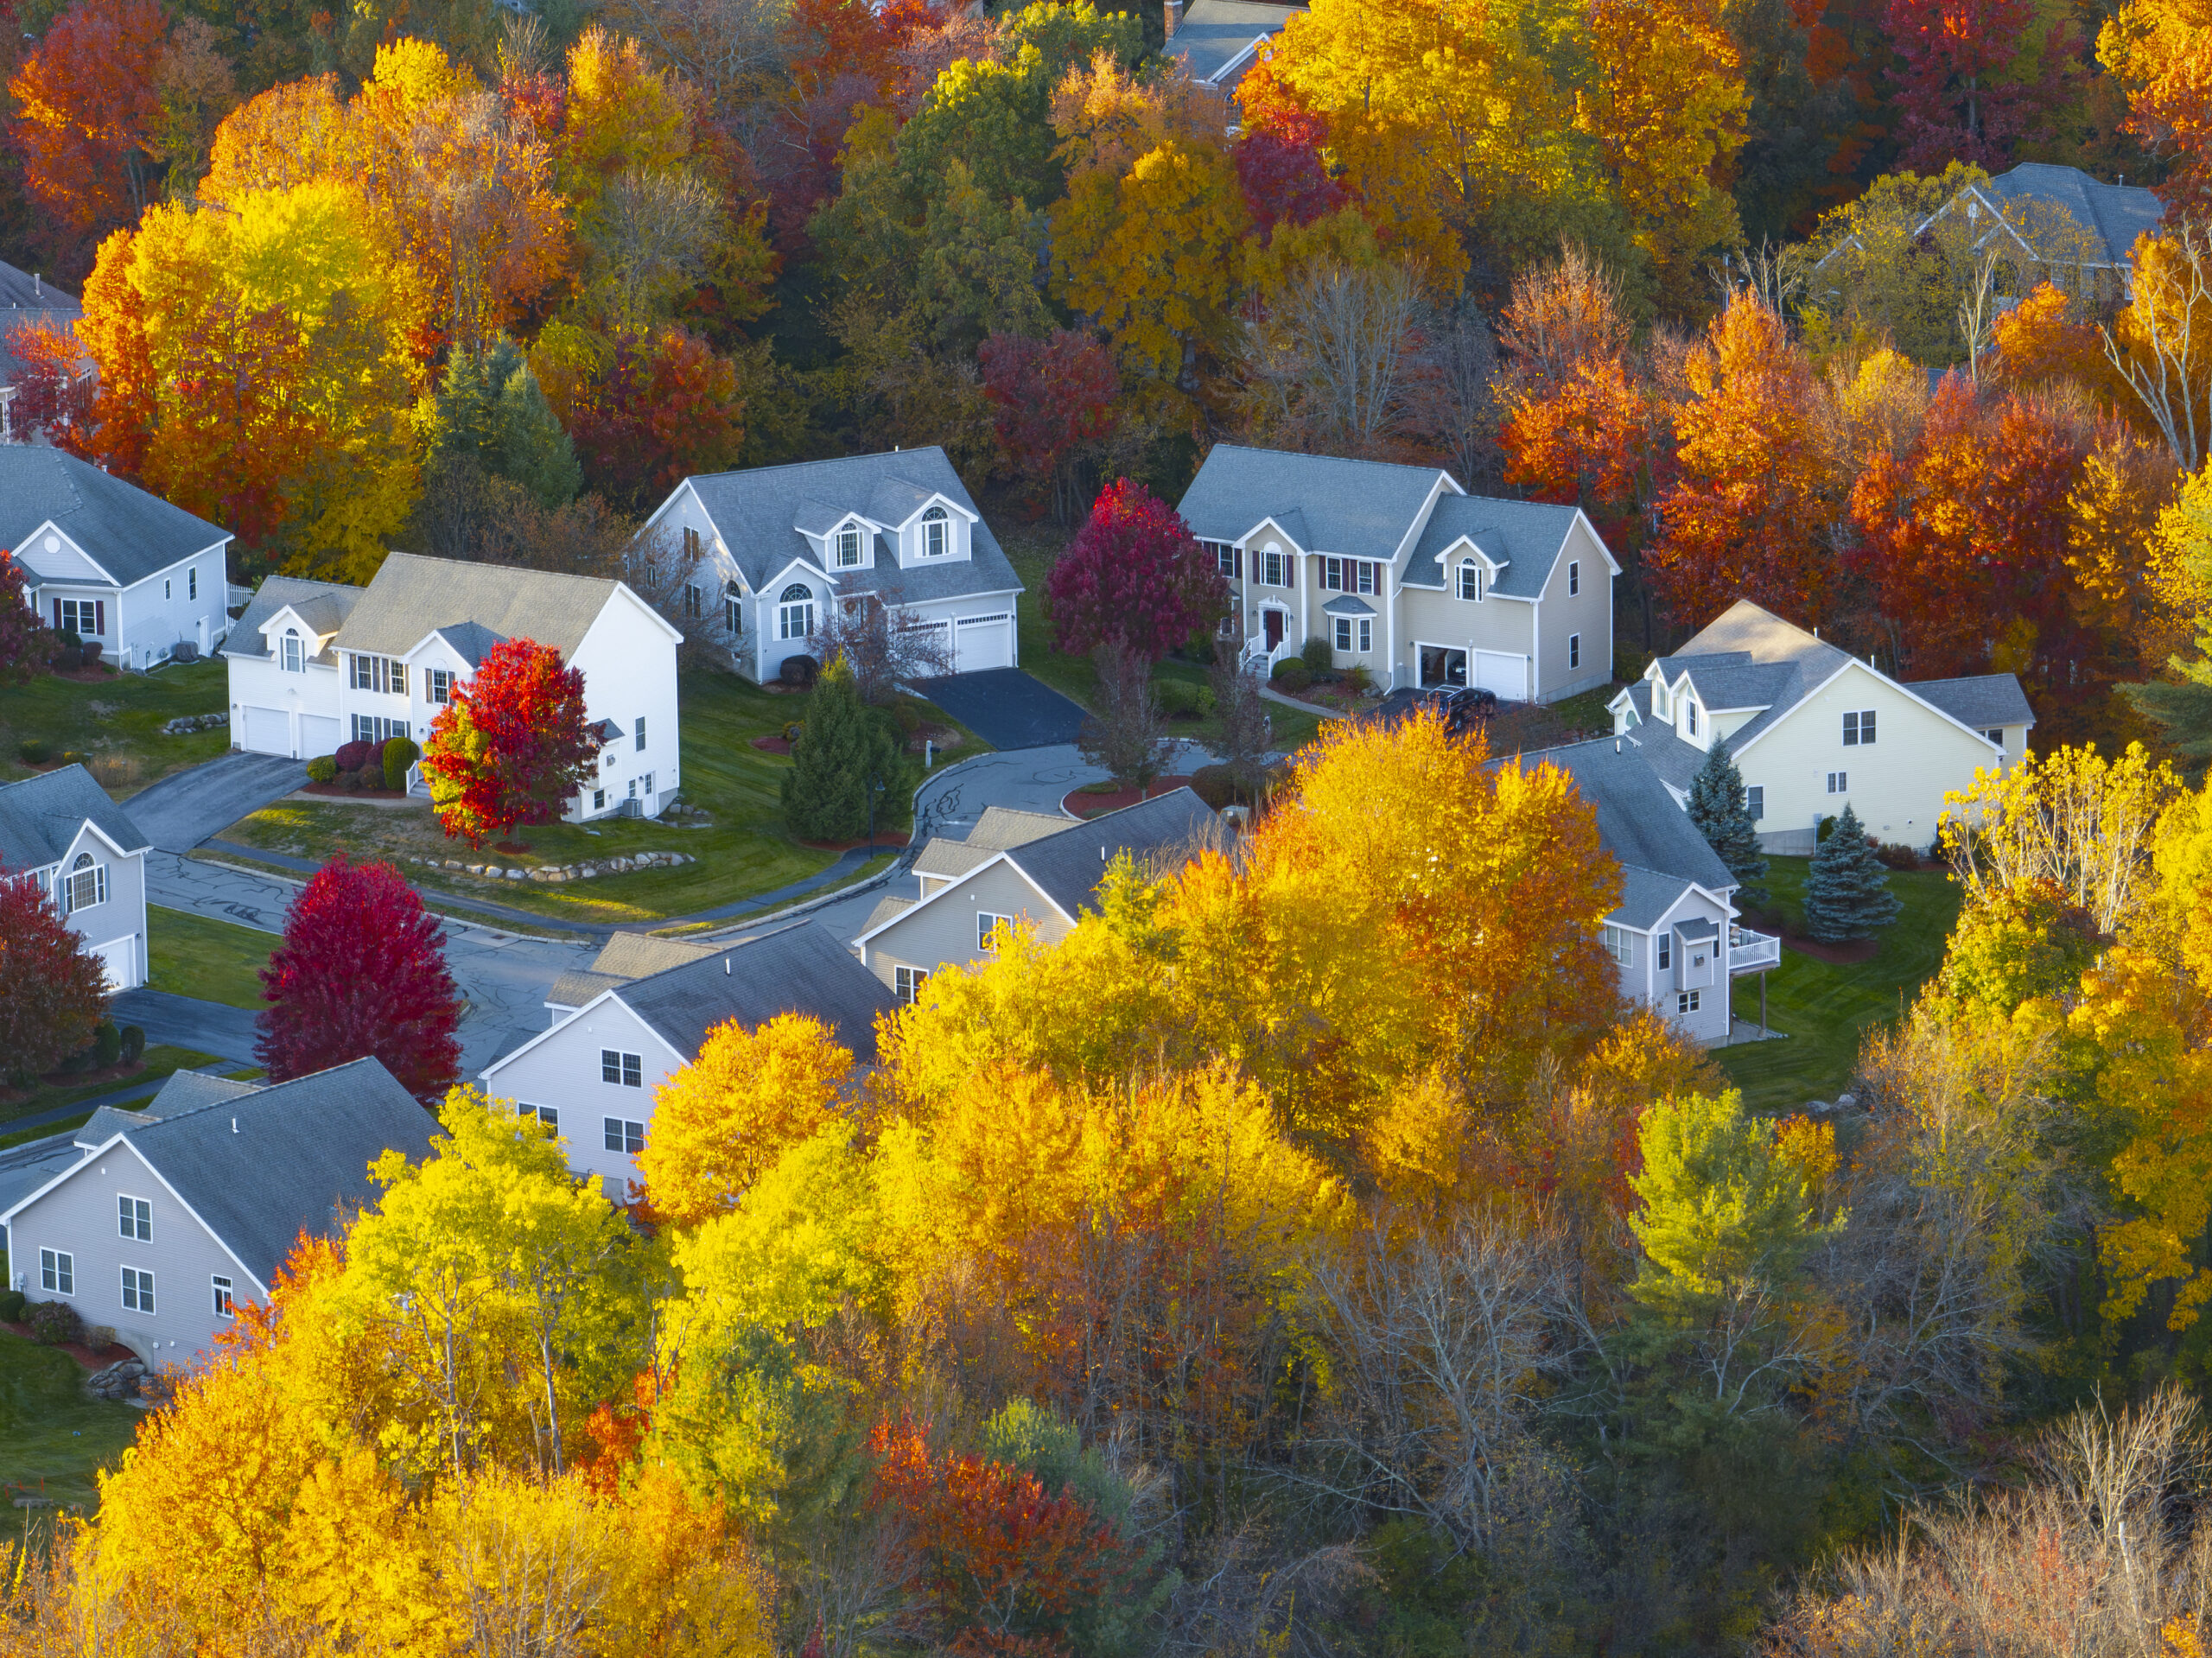
Low housing inventory and high mortgage rates are impacting Connecticut’s fall housing market.
While inventory typically rises in the fall, the latest data shows little growth. Single-family homes for sale dropped 0.7 percent year-over-year in August 2026, with 5,737 units on the market, according to SmartMLS.
The Greater Hartford area, the state’s biggest housing market, only saw slight inventory growth. New listings rose 0.5 percent year-over-year in August 2026, bringing the inventory on the market last month to 3,975 single-family homes for sale, according to the Greater Hartford Association of Realtors.
“We’ve seen an increase in inventory,” SmartMLS President Michael Barbaro said. “It’s not incredibly significant. We’re still at historically low levels here in Connecticut for inventory. We attribute a lot of that to people aging in place and having these very low interest rate mortgages, not wanting to get out of them, not being able to find something that they would like.”
Though underlying demand remains steady, sales volume has lagged all year. SmartMLS reported 22,942 single-family home sales so far in 2026, a 1.8 percent decline compared to the first eight months of 2025.
High Interest Rates Add to Strain
High interest rates can add further affordability strains to consumers. According to Freddie Mac, the average 30-year mortgage’s interest rate increased from 6.35 percent in Sept. 11, 2025 to 6.76 percent in Sept. 10 of this year. Then, in the seven days since then, it hit 6.96 percent.
This has further stressed the importance of accurate pricing in Connecticut, according to real estate agents and observers interviewed in this story.
“You have a lot of sellers that are very overexcited by the market,” said Gen Distance, the CT Realtors 2026 first vice president and broker-owner of Gen Next in Darien. “It’s important for the sellers to really listen to their agents for pricing advice because we see these conditions all day long, and we know the best way to sell a home. Sellers have gotten very excited, and then when they don’t have success, they get very upset with their brokers but it’s usually because they set their own pricing and didn’t listen.”
While sellers could be aggressive in pricing during the pandemic when demand was high, that isn’t the case anymore, according to Barbaro. Along with leading to a property sitting on the market, it can also lead to a lower sales price, he added.
“Overpricing can actually cause you to get less money for your property. Ultimately, [it] sits on the market,” he said. “We haven’t seen that since COVID, and now it’s now it’s here. It’s back, and I’ve seen it affect properties that I was representing buyers, and also where we represented the seller who was trying to capitalize on what was going on in the market or what had gone on in the market in the past. “It’s been an interesting last quarter.”
Seasonality Shifting
While there is typically an uptick in activity after Labor Day, the fall market traditionally slows as the holidays near.
“You do see some seasonal kind of decline in the volume as we ease into the winter months,” PeoplesBank Senior Vice President of Consumer Lending Amber Coughlin said. “If we get an early snow, that certainly can impact us or super cold temps. Living here in New England, that really can dictate how things are going. Then as we near the holidays, people tend to shift their focus less on wanting to sell or buy a home, and more waiting towards that spring market.”
But seasonality isn’t as strong in Connecticut as it was prior to the pandemic, CT Realtors’ Distance said.
“Now that ‘normal’ has shifted, our inventory is pretty much the same,” she said. “You’ll find it kind of dropping off when it’s snowy and icy but fall is a vibrant market. It has been for the past few years.”
Now, with interest rates higher, both buyers and sellers could opt to press “pause” on their move until they see a lower interest rate environment, according to Barbaro.
“Buyers and sellers are looking at the same thing,” he said. “In the past, buyers never had these ridiculously low interest rates that they were locked into. It was varied. That factor is now driving whether or not I sell a house. I have clients personally who would love to downsize, but based on their interest rates and what they’re paying, it’s worth it for them to stay in a larger house that they don’t need than it is to go out and buy something at an inflated price with an inflated interest rate.”
CT Positioned to Ride Out Uncertainty
Additionally, uncertainty around the war in Iran – and the related hit to fuel prices and the trajectory of the economy – can also cause some buyers to have second thoughts on entering the market.
“The biggest impact would tend to be if they think that there’s something that may potentially impact their job,” PeoplesBank’s Coughlin said. If they are going into a new home, it’s most likely more expensive than what their current situation is, so they are going to give that some additional thought.”
Due to a relatively strong local economy, Connecticut buyers are able to withstand these challenges better than other areas of the country.
“The Northeast, particularly Connecticut, is very unique in the sense that a lot of our industry is based in New York and Boston,” Distance said. “People tend to do a little bit better financially in this marketplace, even though all of us are a little tight right now.”